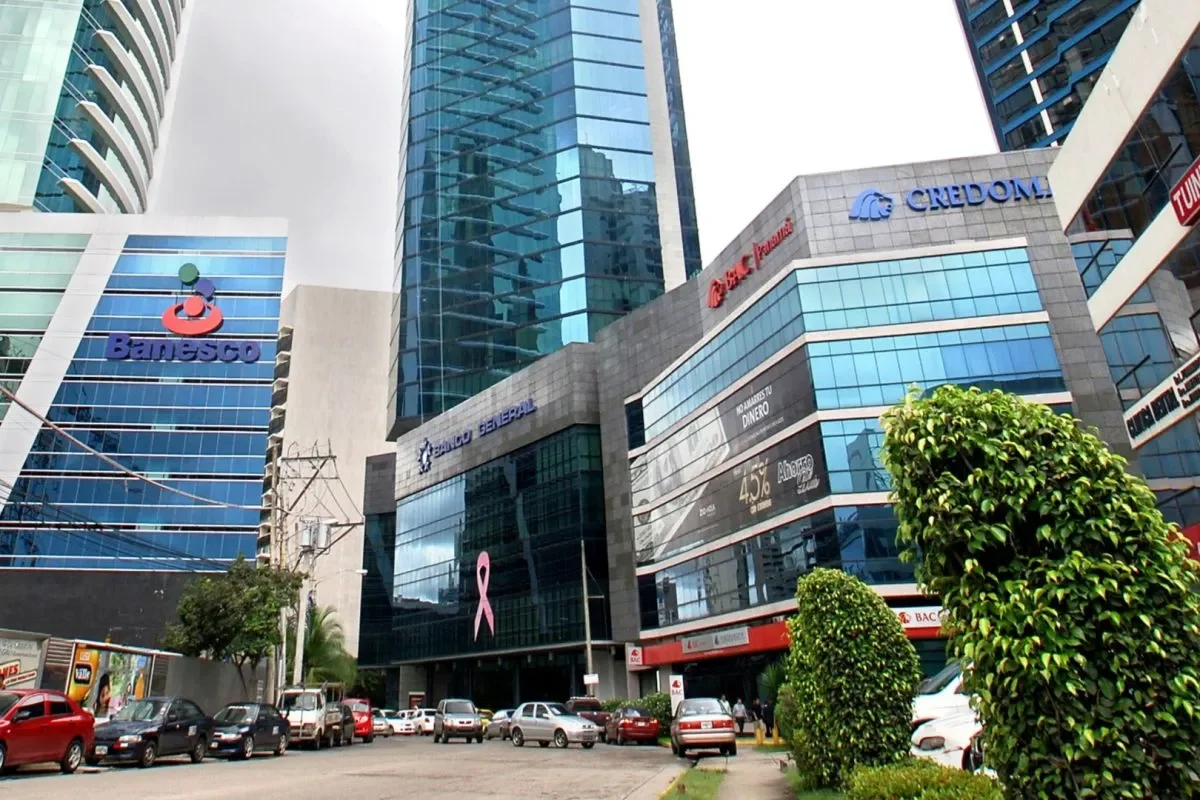
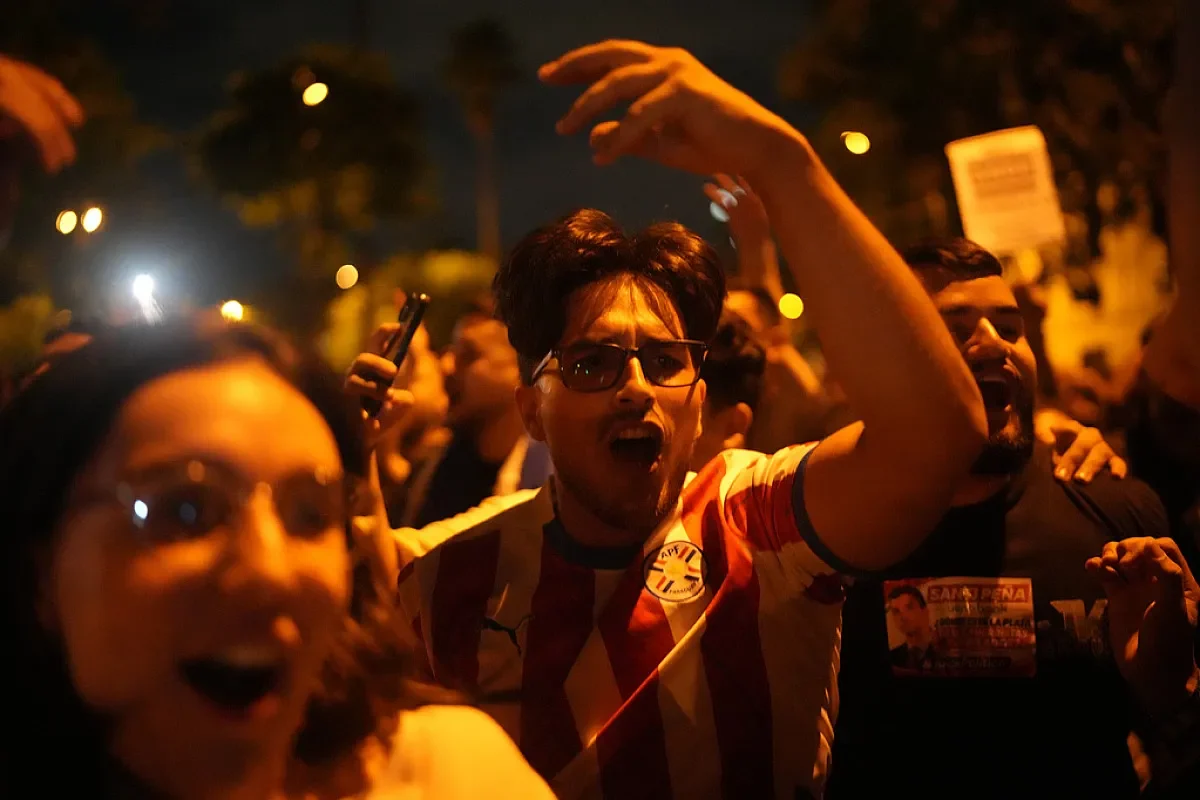
Panama’s banking regulator will launch a feasibility study next year to assess creating a deposit guarantee fund, a move that could reshape Panama banking security and indirectly affect interest rates paid to savers. The decision comes as the collapse of Paraguay’s Ueno Bank and the subsequent political crisis in that country have reignited debate across the region about depositor protections.
The Superintendency of Banks of Panama (SBP) confirmed the study will examine coverage limits, protected amounts, administrative models, financing structures, and how a guarantee fund would interact with existing bank resolution mechanisms. The announcement marks a significant shift for a financial center that has long operated without such a safety net.
Panama Banking Security and the Deposit Insurance Gap
Panama’s International Banking Center currently hosts 38 private banks with general licenses. Of those, 12 are Panamanian-owned, 24 operate with international capital, and two state-owned banks complete the landscape. None currently participate in a formal deposit insurance scheme.
The SBP, led by Superintendent Milton Ayón Wong, acknowledged the topic has been under evaluation for years but said the Ueno Bank intervention brought renewed urgency. In Paraguay, the existing guarantee fund allowed regulators to return at least partial funds to 100% of eligible depositors, covering up to 228 million guaraníes, roughly $37,000 per account.
Funding Model Would Shift Costs to Banks
If implemented, the preferred financing approach would require banks to make periodic contributions to a common fund rather than drawing from savers directly or burdening the state budget. But the SBP cautioned that indirect costs would likely surface through lower deposit rates.
“We consider that indirectly this would have an impact on the interest rate that these banks would pay on deposits that would become covered or protected by said fund” [Translated from Spanish]
The regulator emphasized that any mechanism must account for Panama’s dollarized economy and preserve incentives for responsible bank management. The SBP also plans to present a bank resolution law, a complementary framework that would establish orderly procedures for handling failing institutions.
¿Están los ahorros protegidos en Panamá? La Superintendencia prepara seguro de ahorristas tras bancarrota de# UenoBank https://t.co/68XZvNSY7c
— Mary Triny Zea (@MTrinyZea) November 16, 2026
Regional Comparisons and Expert Perspectives
Amauri Castillo, who served as banking superintendent from 2020 to 2024, said Panama’s regulatory framework “significantly exceeds” Paraguay’s in prudential requirements, risk management, corporate governance, and capital conservation buffers. Yet he urged authorities to revisit the deposit insurance discussion.
“We must resume that discussion and explore a scheme to create a private guarantee fund to secure depositors’ savings” [Translated from Spanish]
Castillo noted the central question remains who would finance such a fund. The SBP maintains that protecting public savings strengthens confidence and stability in the banking system, calling the matter one that “deserves technical and responsible evaluation.”
Implications for Panama’s Financial Center
The feasibility study arrives as Panama seeks to reinforce its reputation as a stable regional financial hub. A deposit guarantee fund would align the country more closely with international best practices, though implementation would require careful calibration to avoid competitive disadvantages.
The SBP’s statement underscored its intent to study global models without compromising the solidity or competitiveness of the banking center. The coming year will determine whether Panama joins the ranks of countries offering explicit deposit protection or maintains its current approach to Panama banking security.